
The equity rally to yet new all-time-highs feels unconvincing. Expectations of inflationary pressures easing and a return to upside growth are not shared by bond markets which are concerned at signals of higher borrowing costs as governments fail to rein in fiscal programmes. A fall in oil prices will help but won’t solve anything.

At the back of all traders and investors minds is the question: “just how bad might the US Midterms be?" Relax. Things are never as bad as we fear, (though seldom as good as we hope). The mid-terms will be consequential, and no matter what the result are unlikely to do much to reverse the long-term decline of the US Treasury Market – the single most important market on the planet.

Keep your eyes on JD Vance. He is headed for a coronation. What will that mean for America and global markets? He’s not stupid, but many suspect hes is not his own man – he owes his successes to billionaire Mega-mind Peter Theil. Vance will lead the attack on the Progressive, Weirdo, Democratic Socialists, but even if he wins… what kind of market and economy might he inherit?
This week is going to be… “interesting”. Confidence in the US financial markets and system is under pressure. The US owes more than $40 trillion. Bessent’s intervention in bond markets has backfired, the market is waiting to judge new Fed Head Kevin Warsh, and Trump has kicked off a new trade war with Canada. The USA’s Virtuous Sovereign Trinity of the Dollar, the Treasury Market, and Political Competency looks well-wobbly. Meanwhile, the latest documentary on Boeing shows how the myth of US exceptionalism is under pressure.
With US debt about the breach $40 trillion, Scotty Bessent intervened to stem rising long-end yields. The market loved it, but the reality is that distorting interest rates has all kinds of consequences. That includes the risk an economy focused entirely on financial returns isn’t spotting or addressing real world threats to jobs, growth, conflict, the environment and climate. Maybe it’s time to let rates normalise?
19 months of Donald J Trump have been extraordinary – the unravelling of alliances, the forever war with Iran, and the belated discovery that financial clout doesn’t translate into geopolitical power. While the Mid-terms may make Trump a lame-duck, the consequences of Trump will hamstring the USA for decades and colour a new economic reality.
The real strength of the US economy is not its military or the dollar’s exorbitant privilege, but the depth of its capital markets - which have financed the most successful economy in history. The risk is not how large the US deficit is, but how sustainable are America’s capital markets to mounting fiscal pressures, market shifts and geopolitical forces?

Sometimes you just have to laugh. The Tariff Judgement against Trump raises elevated Chaotic Tantrum risks in Treasuries, while markets fear what wobbles in private credit might conceal. Everything in markets are connected – when something cracks in credit, someone somewhere else will start screaming!
If there is one thing we Brits are really, really good at its making things difficult for ourselves. We talk ourselves down and fall into doom and gloom, despite knowing for certain is the sun will come up tomorrow… “Things are never as bad as we fear, but seldom as good as we hope!”
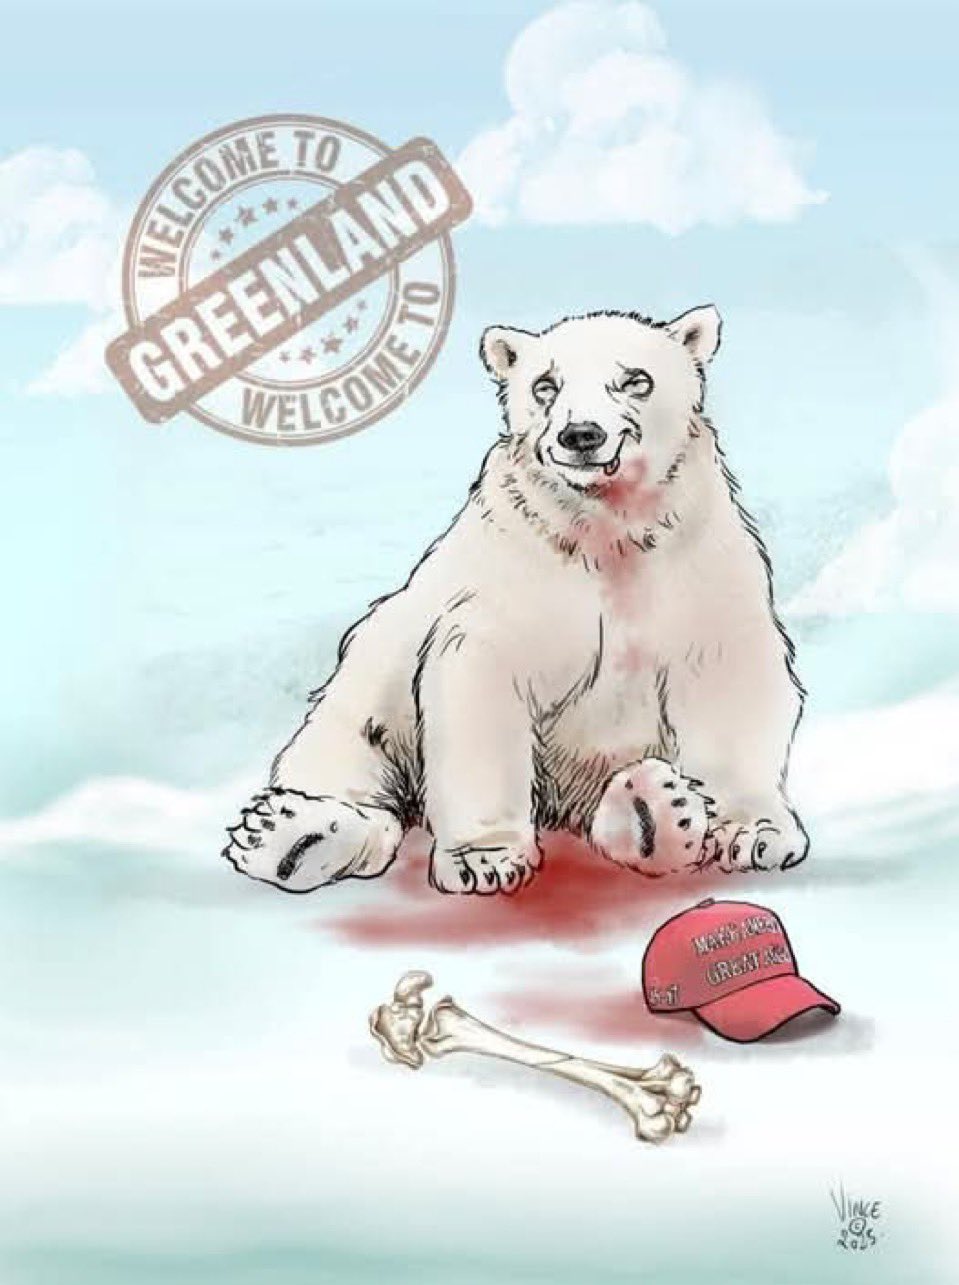
So much to worry about. Stop. Why bother? What’s not to like about short-term markets. Nvidia is selling more and more and more chips, SpaceX half-circumnavigated the planet, and US Treasuries care not a jot about Fed Independence. Give me another puff of whatever these guys are smoking!
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel