
To avoid war we must be prepared to fight – that a basic dictum from history. While the conflict pressures mount, and political systems are increasingly strained, the defence of Western Economies in a post-Nato era will require massive private capital investment. But many investors are not prepared to step up and finance defence. It’s an attitude that has to change.
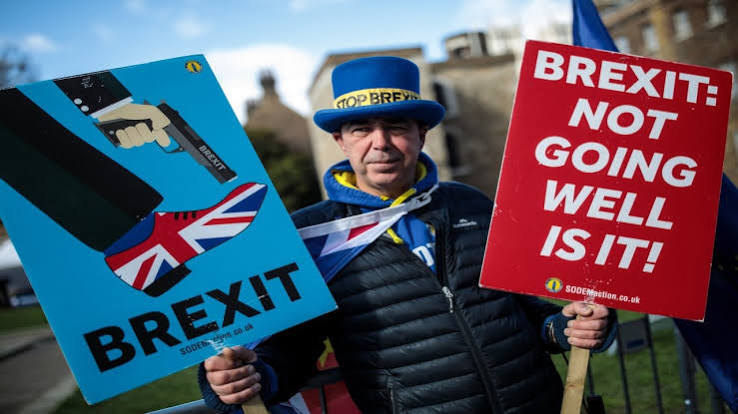
The Brexit Debate is never going to end. But the UK and Europe need to look to the future. The World in 2026 is very different to what short-term populist politicians thought they were selling us in 2016. A new relationship around trade, cooperation, and security, is possible and positive. Moreover, there is an easy win that could accelerate European growth – strengthening and unifying European Capital Markets!

Charlie Munger’s triad has manifested perfectly: Liquor is the intoxicating narrative of infinite AI scaling that defies gravity. Ladies is Ms. Alice Huang, the alleged spy who compromised the King. And Leverage is Nvidia itself—the underwriting spider at the centre of a massively leveraged web of debt and circular financing.

This is looking a critical week for AI. Some market watchers see last week’s wobbles as a brief bout of indigestion with the market poised for further gravity defying upside. Or have we already seen Peak-AI? The most likely clues on direction are not in stock prices, but in bond spreads, where traders are rightly concerned there is a mismatch between spending and likely revenues!

Elon Musk has been described as the biggest loser from the Blue Tsunami midterms – what will it mean for his firms’ valuations, and his future influence. We need to know what really went on between Musk and Trump. Even more critical is the utility of SpaceX’s technology and Starlink’s satellite constellation as a Strategic Resource. Some tough decisions, but sensible choices lie ahead.

All is not smooth in the credit markets. There are signs of change upon the waters and in the sky. Spreads are widening, liquidity has got tight, and now we have a fund in serious trouble even as corporates try to raise as much as possible before rates rise or markets stall. The hyperscalers are having to pay up for debt – and that’s likely to drag spreads higher. I see trouble ahead…

Democracy wins. Trump was rejected by American voters, but his legacy will remain. The damage to done to the economy, the institutions of state, the constitution, and global power will shape America and geopolitics for decades. It’s unclear how the rest of Trump’s lame duck presidency will play out, but Corruption and the nexus of Wealth and Power will come under massively heightened scrutiny. Should the next US administration nationalise SpaceX?
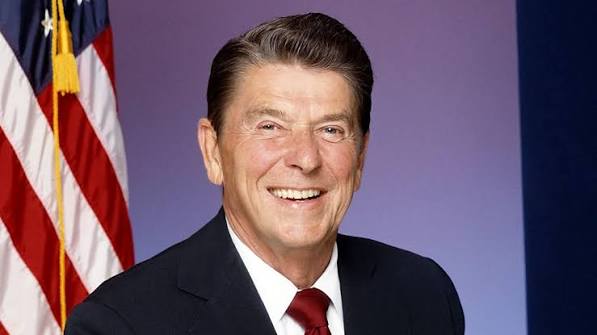
Today’s US Midterms are a Referendum on the Presidency – and will be consequential for global markets. The result will depend entirely how many Republicans are still minded to Vote for MAGA. They might want to think back to an earlier age, the Republican President Ronald Reagan, and ask what the current incumbent and Reagan have in common, if anything.
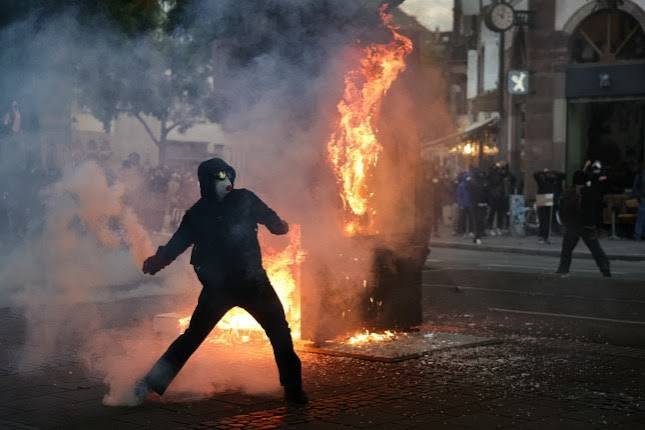
Rising market instability looks inevitable as the AI meltdown, the US Midterms and European political riots, and the geopolitical risks from the US vs China hegemonic challenge reach crisis points concurrently. It’s a classic Three Body Problem – making it almost impossible to logically predict what happens next. Sit back and watch for the opportunities – they will emerge, but not where you expect them.

Nobody wants to pay taxes or spend money on defence. But both are inevitable. Investment in security has the potential for significant returns for investors and can drive considerable economic gains for nations that spend wisely. History is written by the victors, but the costs of underfunded defence are very clear – ask the losers how well scrimping on Defence worked for them.
Porridge ArchiveSteve Lowsley2025-10-22T14:16:14+01:00