
This is looking a critical week for AI. Some market watchers see last week’s wobbles as a brief bout of indigestion with the market poised for further gravity defying upside. Or have we already seen Peak-AI? The most likely clues on direction are not in stock prices, but in bond spreads, where traders are rightly concerned there is a mismatch between spending and likely revenues!

All is not smooth in the credit markets. There are signs of change upon the waters and in the sky. Spreads are widening, liquidity has got tight, and now we have a fund in serious trouble even as corporates try to raise as much as possible before rates rise or markets stall. The hyperscalers are having to pay up for debt – and that’s likely to drag spreads higher. I see trouble ahead…
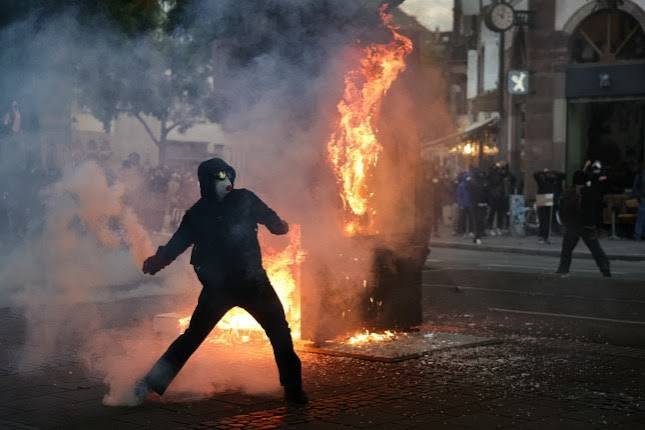
Rising market instability looks inevitable as the AI meltdown, the US Midterms and European political riots, and the geopolitical risks from the US vs China hegemonic challenge reach crisis points concurrently. It’s a classic Three Body Problem – making it almost impossible to logically predict what happens next. Sit back and watch for the opportunities – they will emerge, but not where you expect them.
The US treasury market is the deepest and most liquid market on the planet. But over the last year, foreign investors have been walking away. Why? Is it simply fear of a bear market from rising inflation and the rising quantum of US debt, or the sheer scale of the refinancing required. Or is it more fundamental in terms of geopolitics, a changing investment market, and better returns elsewhere. If so, it’s a lesson every country should absorb.

Global conflict risks are rising. The wars in Ukraine and the Gulf are the openers. However, a global conflict for hegemonic power between China and the USA is more likely to take the form of “Grey” conflict than outright “kinetics” between them – triggering further inflation threats, political and economic disruption, and supply chain destabilisation driven by ongoing cyber-attacks, fake news and regional conflict. The resilience of nations will be the critical factor – and that means being prepared to defend themselves.

Consequences spread like ripples on a pond. Trump lobbed the bloody great rock of the Iran War into the global economy earlier this year. Now the risks he raised are converging. Inflation, Rates, Trade, Geopolitics and Conflict were thrown into stark relief over the weekend as Trump further roiled markets, and climate risks will be extra spice. How this ends is unclear…
The equity rally to yet new all-time-highs feels unconvincing. Expectations of inflationary pressures easing and a return to upside growth are not shared by bond markets which are concerned at signals of higher borrowing costs as governments fail to rein in fiscal programmes. A fall in oil prices will help but won’t solve anything.

This morning something different. A review of Robin Wigglesworth’s new book, A Fabulous Debt, on the history of the Bond Markets. Great read and absorbing. It’s a broad brush explaining how bonds have evolved and developed. Bond markets guide far more than just interest rates – they are power, political stability, and can drive market instability. In Bonds there is truth. The book leave interested readers wanting to know more in terms of the consequences of the Bond Markets and mechanisms.

Robert Hillman is a highly experienced City Quant, with a legendary record. He’s also a great mate of Bill! He’s come up with a great analysis of the UK’s Triple Lock Pension policy – looking at it as an option... It's well worth reading if you want to figure out smart policy vs political games.
Yesterday UK premier Andy Burnham made clear the 15-year-old promise to keep rising the UK basic pension is going to change. The government will reinvest the cash it saves in a new national care service.

What should markets be thinking about Andy Burnham’s conference speech yesterday? Gilts look to be giving him the benefit of doubt. Good in parts? He spoke well, proposed some positive policies and ideas, and gave an impression of a confident, positive politician set to deliver. The real issue isn’t just can Labour hold the nation steady and reverse years of negativity and low growth, but can any of the other parties do any better given the constrained state of the national finances?
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.
If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel