

It really does feel the Atlantic Ocean got much, much wider. As Europe struggles with riots and populism, financiers in the USA dismiss Yoorp as irrelevant, and think their economy is doing just great, fuelled by the AI boom and rising earnings. What they miss is the vulnerability of the economy to a debt shock and rising Treasury refinancing risk.

Consequences spread like ripples on a pond. Trump lobbed the bloody great rock of the Iran War into the global economy earlier this year. Now the risks he raised are converging. Inflation, Rates, Trade, Geopolitics and Conflict were thrown into stark relief over the weekend as Trump further roiled markets, and climate risks will be extra spice. How this ends is unclear…

In Bond Markets there is truth – and they are flashing warning signals a systemic market reset is on the cards. As rates rise, the relative prices of all financial assets will be impacted as the price of money normalises. It’s a period of transition with a high chance of an unstable reset, which is magnified by QE setting a false expectation of long-term low rates, and the growing realisation financial systems will suffer from political incompetence.

Global Bond yields remain… fragile. As the US breaches 5% 10-year yields, the UK is now slowing QT which should be market positive. It’s high time the Bank of England and the UK Treasury (which famously pretend the other doesn’t exist) cooperate on liability management to address the UK’s debt pile – which is actually in much better shape than the right-wing press would have you believe.

Keep your eyes on JD Vance. He is headed for a coronation. What will that mean for America and global markets? He’s not stupid, but many suspect hes is not his own man – he owes his successes to billionaire Mega-mind Peter Theil. Vance will lead the attack on the Progressive, Weirdo, Democratic Socialists, but even if he wins… what kind of market and economy might he inherit?
The coming year is likely to be shaped by higher inflation from energy and El Nino, rising interest rates, “policy-mistake” risks, and revaluation risks as capital markets adapt to rate normalisation. Looming over it all be political noise. Understanding where we are, how we got here and what happens next will be critical.
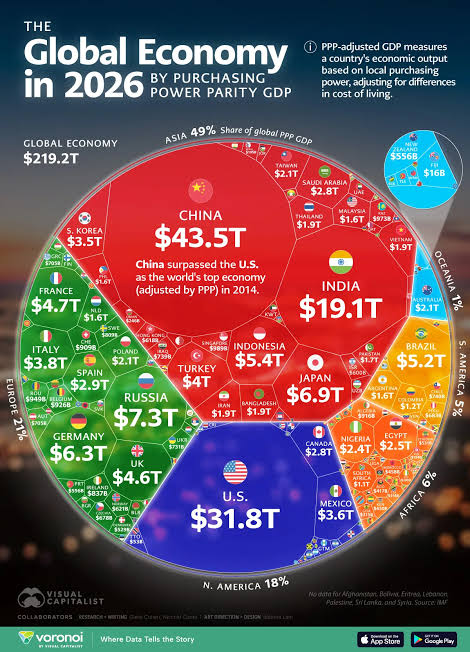
Is a financial crisis coming our way? US Debt, Inflation, Trade, Energy, AI concerns and the rest pushed the revealed wisdom of new Fed Head Kevin Warsh out the limelight last week. Bond yields continue to rise. There are now growing fears of slowdown, or worse. Cheer up! Not the end of the World. But if a financial crisis is coming it will reflect lessons from the past on liquidity, but to solve it we also must acknowledge how much the world has changed since the last one in 2008. This time it will be different!
This week is going to be… “interesting”. Confidence in the US financial markets and system is under pressure. The US owes more than $40 trillion. Bessent’s intervention in bond markets has backfired, the market is waiting to judge new Fed Head Kevin Warsh, and Trump has kicked off a new trade war with Canada. The USA’s Virtuous Sovereign Trinity of the Dollar, the Treasury Market, and Political Competency looks well-wobbly. Meanwhile, the latest documentary on Boeing shows how the myth of US exceptionalism is under pressure.

In the past 15 years the US economy has left Europe in the rear-view mirror. While America booms, Europe appears to be flatlining. The question is why? Americans say it’s entirely Europe’s fault: bad policies, failing politics, and lack of unity. However, the consequences of the (as yet unresolved) European Sovereign debt crisis triggered by the Global Financial Crisis of 2008 was the speedbump.
The UK is not about to disappear in a puff of smoke because the Gilts Market is having a minor tantrum. But there is a serious Political Competency premium on Gilts, which will rise when the scale of Labour’s defeat becomes apparent, and the Starmer premiership is up against the wall. Trouble ahead.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel