

Markets are worrying about a short-term interest-rate/inflation triggered correction, but something deeper may be approaching – a convergence between market, economic and political failures. It may be time to hedge against consensus expectations of “it will all be fine” and focus on factors like national resilience in terms of what nations thrive and which won’t!

In Bond Markets there is truth – and they are flashing warning signals a systemic market reset is on the cards. As rates rise, the relative prices of all financial assets will be impacted as the price of money normalises. It’s a period of transition with a high chance of an unstable reset, which is magnified by QE setting a false expectation of long-term low rates, and the growing realisation financial systems will suffer from political incompetence.

Global Bond yields remain… fragile. As the US breaches 5% 10-year yields, the UK is now slowing QT which should be market positive. It’s high time the Bank of England and the UK Treasury (which famously pretend the other doesn’t exist) cooperate on liability management to address the UK’s debt pile – which is actually in much better shape than the right-wing press would have you believe.

Keep your eyes on JD Vance. He is headed for a coronation. What will that mean for America and global markets? He’s not stupid, but many suspect hes is not his own man – he owes his successes to billionaire Mega-mind Peter Theil. Vance will lead the attack on the Progressive, Weirdo, Democratic Socialists, but even if he wins… what kind of market and economy might he inherit?
The coming year is likely to be shaped by higher inflation from energy and El Nino, rising interest rates, “policy-mistake” risks, and revaluation risks as capital markets adapt to rate normalisation. Looming over it all be political noise. Understanding where we are, how we got here and what happens next will be critical.
In Bonds there is truth. While government bond yields have risen some 40-50 basis points since the Iran War, and yield curves have steepened, we are not in crisis territory yet. However, the risks of “higher for longer” rates, and sustained inflation have risen. These will impact credit markets and potentially trigger a cascading corporate crisis – leading to all kinds of hell that governments and central banks are now ill-equipped to deal with.
The UK is not about to disappear in a puff of smoke because the Gilts Market is having a minor tantrum. But there is a serious Political Competency premium on Gilts, which will rise when the scale of Labour’s defeat becomes apparent, and the Starmer premiership is up against the wall. Trouble ahead.

The War/Not War in the Gulf rambles on – and the consequences mount. Careless markets are becoming anesthetised to the news – raising the risks of a shock destabilisation. The big question is what will follow? Who will be the winners from Trump’s misbegotten war?

When staring down the abyss of looming stagflation, a bond market rout, and a reset on the global economy… let’s try to pretend it’s all something else. Christine Legarde would have made a great French President. Of course it’s not Stagflation... it’s just... Well? What is it?
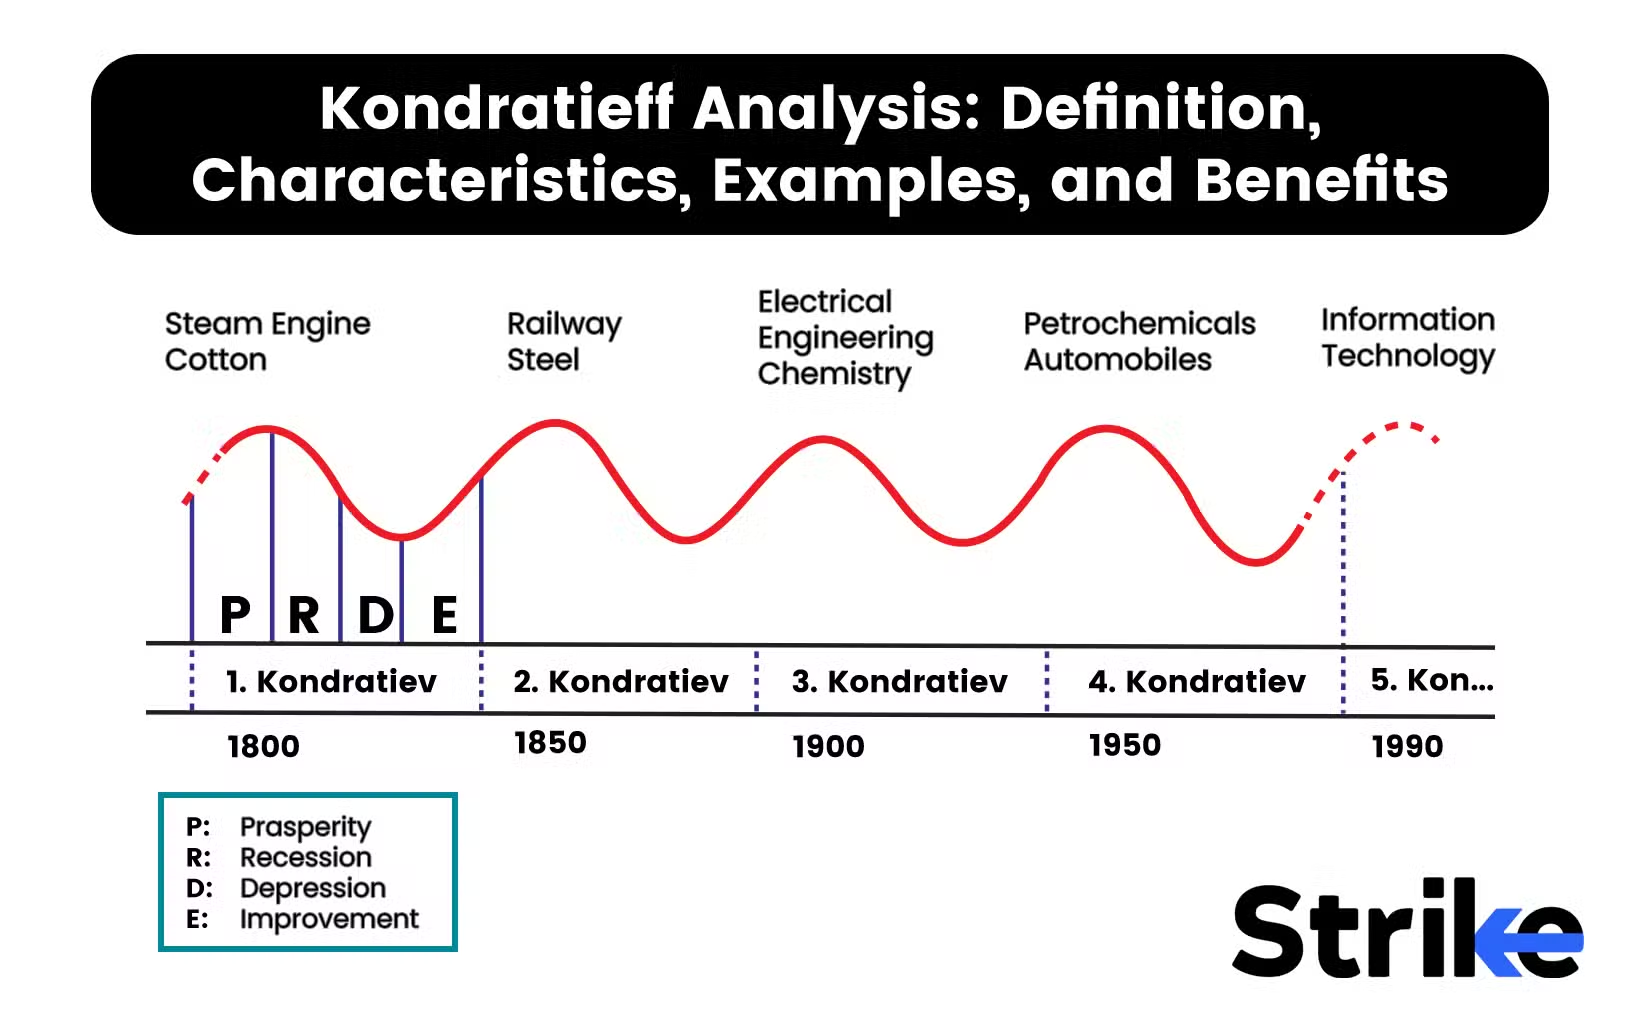
The markets are on a tear convinced normalisation is around the next corner. Yet they ignore the reality the Iran war has done significant damage to the global outlook – even if Tehran and Washington kiss and make up tomorrow. I don’t claim to understand the madness of markets and their ability to keep fooling themselves, but I do follow economic history and how events change outcomes.

Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel