
The Russians are masters of Maskirovka, the art of distraction, disinformation and misdirection. After sabotaging the transatlantic economy, the next stage is to destabilise Europe and break its resilience by fermenting social unrest, political conflict, and riots. The current waves of protest are likely to erupt across Europe with the potential of triggering a bond crisis, are deliberate and part of a hostile plan to remove Europe from the board.

French political instability and it’s looming fiscal crisis will distract and delay the European project of a shift towards “strategic unity” in the face of a) the immediate security threats from Russia, and b) the long-term geopolitical shift towards China at the end of the Transatlantic American age. How Europe responds to the growing French threat could determine its economic outlook for decades.
The French Bond market threatens to become a crisis as yields widen and its’ politics look increasingly a zero-sum game. While we’ve been watching the antics in DC and the price of oil due to Iran, we’ve missed how swiftly a new European debt crisis has been brewing. If it deepens, it won’t be a simple repeat of 2010-12, which nearly crushed banks and triggered defaults. Europe’s second largest economy in crisis, and dispute with Frankfurt, could trigger even more massive instabilities.
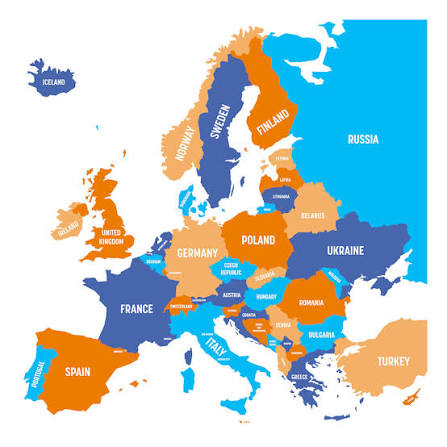
Europe is a diverse, culturally rich and fascinating continent but increasingly looks an economic basket case facing economic and demographic decline. Its suffering economic PTSD after successive shocks in Banking, Sovereign Debt and now Energy. Now it’s being squeezed between an unreliable USA and China’s proxy, Russia. Maybe that’s the challenge it needs?
Trump is the most unrestrained US president – yet is supported by the richest and most successful men in America even as we watch him upend everything the USA once stood for. What if Trump is just the front-man for a Regime that is changing the World - breaking traditional relationships and alliances to create a stronger America as China threatens to supersede it? Europe is struggling with the new rules of America’s primacy, the end of the Nato Era, the emergence of a new American hemisphere, and how nations should relate to the new Imperial USA. How these will all play in the Great Game to be Global Hegemon is as yet unclear, but the world is changing fast.
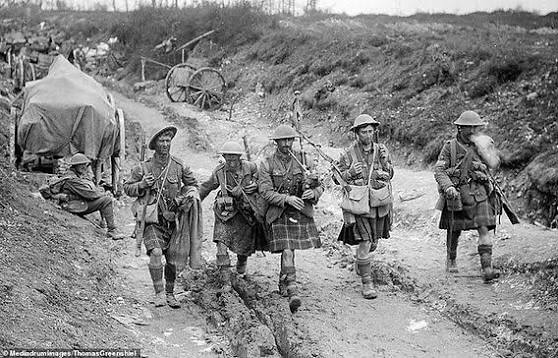
Tensions between Moscow and Europe are rising. There are rumours of war. While Western nations seek to rearm and adopt the lessons learnt by Ukraine, a bubble has developed in Mil-Tec arounds autonomy and drones. Defence investment is not a speculative opportunity – but a key issue for the sustainability and longevity of nations. It’s a complex investment landscape that requires specialist expert knowledge.
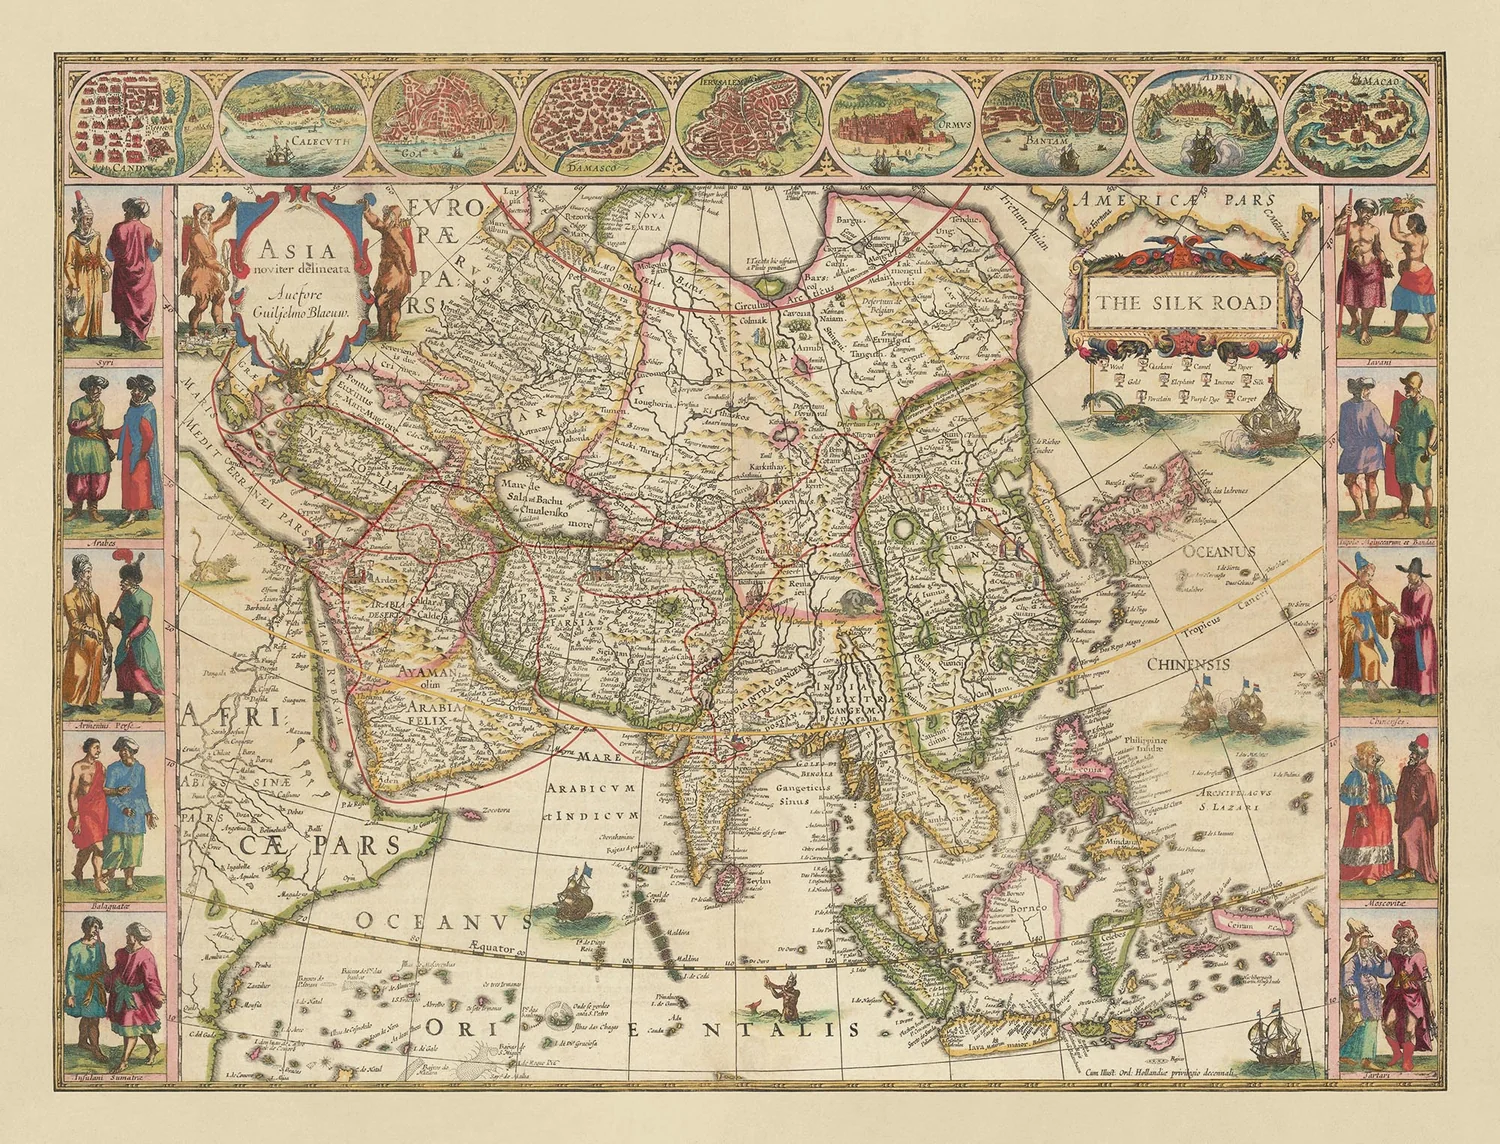
One rule of finance is “follow the money”. The ructions and rising doubts on the sustainability of the US Treasury Market and dollar in the evolving post-US era economy means it may be time for investment transition strategies – where will the future lie? What aspects of US and other Western Democracies will thrive, and how much more investible will China and, perhaps, India become? What are the risks?
C’mon. England won, but Norway was sparkling. It’s a genuine shame they are out the World Cup, but didn’t they do well? There is much that Norway’s successful blend of capitalist social democracy could teach the rest of the West. Most countries squander their abilities and resources – not Norway.

When staring down the abyss of looming stagflation, a bond market rout, and a reset on the global economy… let’s try to pretend it’s all something else. Christine Legarde would have made a great French President. Of course it’s not Stagflation... it’s just... Well? What is it?
Defence is among the most difficult areas to invest. Who would become an analyst after 30-years as a Cinderella sector in the wake of ESG and peace dividends? Now, the imperative for new defence investment is crying out for private capital. That puts a clear premium on knowledge, contacts and skill to invest. Here is a solution.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel