

Markets are worrying about a short-term interest-rate/inflation triggered correction, but something deeper may be approaching – a convergence between market, economic and political failures. It may be time to hedge against consensus expectations of “it will all be fine” and focus on factors like national resilience in terms of what nations thrive and which won’t!
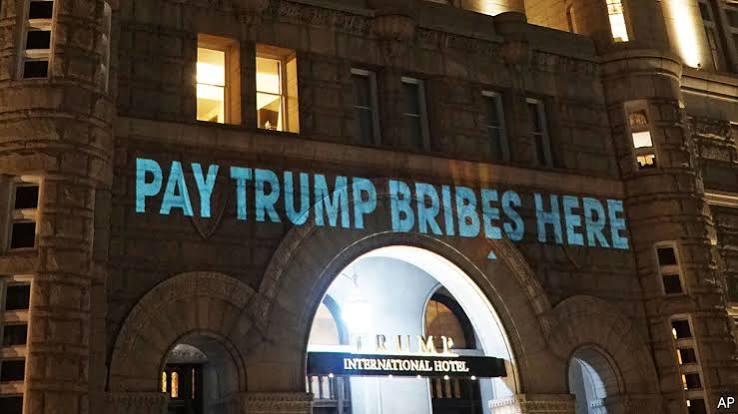
Kevin Warsh established a degree of credibility for the Fed and himself yesterday by hiking rates. The Fed is focused on fighting inflation – the best long-term option, but a short-term painful outcome for American voters. The coming electoral cycles in the USA, Europe and the UK will all highlight the power of money that’s driving the narrative. Big money from Crypto and Tech is driving political decisions. The electorate will suffer the consequences of policies set to elicit donations rather than foster long-term growth and economic security.

Global Bond yields remain… fragile. As the US breaches 5% 10-year yields, the UK is now slowing QT which should be market positive. It’s high time the Bank of England and the UK Treasury (which famously pretend the other doesn’t exist) cooperate on liability management to address the UK’s debt pile – which is actually in much better shape than the right-wing press would have you believe.

Stock Markets partied higher yesterday, utterly unbothered by the optics of the Iran Deal. Bond markets look at the long-term risks – wondering what the consequences of the Iran war might trigger in the coming years when today’s new bonds are set to repay. Traders will be trying to figure out what a new world will look like, and just how sustainable US Bonds markets might be as the global economy shifts.

Western economies succeed because bond and stock markets work together. Bond markets enable governments to finance the optimal conditions for invention and innovation, enabling growth and prosperity. Sometimes Markets fall out of line, while Politics are ruled by votes rather than experience – and that’s where the wobbles start to multiply.
In Bonds there is truth. While government bond yields have risen some 40-50 basis points since the Iran War, and yield curves have steepened, we are not in crisis territory yet. However, the risks of “higher for longer” rates, and sustained inflation have risen. These will impact credit markets and potentially trigger a cascading corporate crisis – leading to all kinds of hell that governments and central banks are now ill-equipped to deal with.

Does the steepness of the US yield curve tell us the US Economy is about to boom, or inflation is about to sink the Treasury markets? To figure out which, you need to interrogate the witnesses and look at what the evidence is telling us.
Y’day we had yet another Judder Moment for markets as the Fed surrendered to Trump and prepares to juice the markets with renewed QE. Have we learnt nothing? No, I guess we have not. Pretend and keep pretending as we enter the Potemkin Economy era. This will not end well.

The UK survived yesterday’s Pretend and Extend budget. It was a lacklustre soap-opera moment. It won’t cure the UK’s long-term issues or fix Broken Britain. If politicians were serious about repairing the political economy of the UK – it’s time for root and branch surgery on the “frictions” that leave the nation suffering Economic Dementia!

Yesterday saw bad political theatre in the UK. Rachel Reeves got up and warned everyone it’s going to be bad and therefore made it so. Acres of negative coverage and lots for the opposition to make noise about. But the reality is maybe very different. There is not that much [more than usual] to worry about.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel