

The War/Not War in the Gulf rambles on – and the consequences mount. Careless markets are becoming anesthetised to the news – raising the risks of a shock destabilisation. The big question is what will follow? Who will be the winners from Trump’s misbegotten war?

When staring down the abyss of looming stagflation, a bond market rout, and a reset on the global economy… let’s try to pretend it’s all something else. Christine Legarde would have made a great French President. Of course it’s not Stagflation... it’s just... Well? What is it?
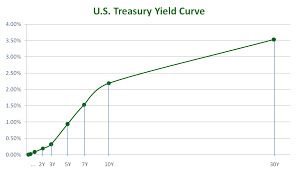
Does the steepness of the US yield curve tell us the US Economy is about to boom, or inflation is about to sink the Treasury markets? To figure out which, you need to interrogate the witnesses and look at what the evidence is telling us.

Sometimes you have to laugh. Tariffs have been the cornerstone of Trump’s economic miracle, allowing him to deflect, discombobulate and distract voters from economic truths. Now the NY Fed says tariffs are a consumption tax – even MAGA voters will be worried as the Mid-Terms approach.
The nomination of Kevin Warsh as next Fed Chair has been rationalised as positive for stability and managing Trump. But will a new name on the desk means certainty will return? Nothing really changed within the Administration – Trump remains Trump and has a massive War Chest to fight the coming bitter Midterms.

Trump has shattered conventions on politics and diplomacy so why not financial markets as well? The Show Trial of Jerome Powell will see Trump seize the levers of monetary policy. For markets its dead simple – what will it mean for the economy and the rising prospects of a Stagflationary Bust in the US?
Markets have opened strongly in 2026 and seem remarkably sanguine towards rising geopolitical instability and shocks. They’re buying a rosy outlook of rising profits, lower rates and costs, and are blithely unconcerned by the risks of destabilisation from conflict or competition.
The Chinese curse about living in “interesting times” is a boon to anyone fascinated by markets. There is no shortage of excitement coming our way next year – everything from conflict threats, renewed inflation, the return of QE, to the Space X IPO. But the thing is… we really don’t know….. we never have!
Y’day we had yet another Judder Moment for markets as the Fed surrendered to Trump and prepares to juice the markets with renewed QE. Have we learnt nothing? No, I guess we have not. Pretend and keep pretending as we enter the Potemkin Economy era. This will not end well.
There is a lot of noise in Gilts these days. The danger is it derails national confidence – even though much of the clamour is twaddle. The reality is all Governments face challenges, but the UK’s Gilts market is much stronger and more resilient that the right-wing press would care to admit.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel