

If there is a 10% chance AI is going to kill us all, then that’s probably bad news for bond markets. There are a lots of things that threaten us, but fortunately most of them are quite unlikely. A 1 in 10 chance we’re all toast is not. Global markets will probably choose to look the other way, but how would your own investment decisions change if you knew the Terminator is about to knock on the door?
The coming year is likely to be shaped by higher inflation from energy and El Nino, rising interest rates, “policy-mistake” risks, and revaluation risks as capital markets adapt to rate normalisation. Looming over it all be political noise. Understanding where we are, how we got here and what happens next will be critical.
The Chinese will be delighted. Western Economies are increasingly polarised and fractured. The US president calls anyone opposing him a “Communist”. The Right Wing threatens mass deportations, while the new emerging Populist Left is demanding redistribution and equality. Destabilising Western Democracies through fake news and disinformation is destroying the resilience of nations to resist. How should markets react?

The Pope has published an Encyclical warning on the risks of an ill-considered rush towards AI. It comes at a time when AI is driving the markets, and AI leaders are whispering in Trump’s ear that regulation will destroy America’s lead. It’s not just the risk we will be turned to grey gloop by AI overlords, but how jobs, the economy, inequality and social equality are at all in play.
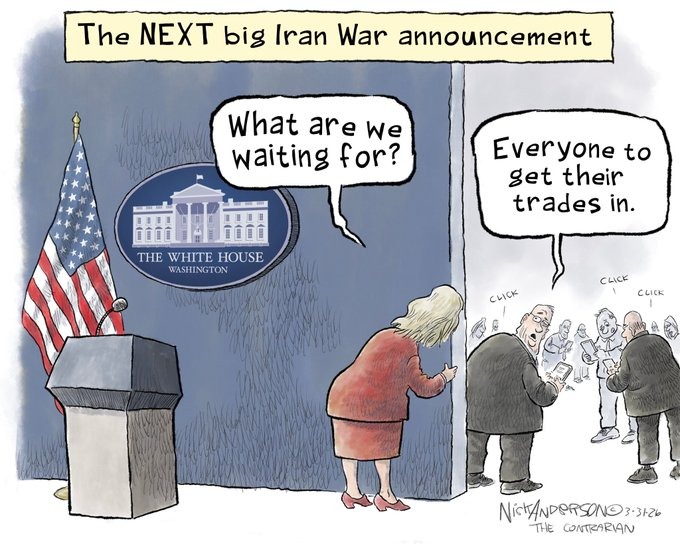
Oh dear. Last night’s explanation of the War did not go well. What changed except a more unstable and fractured global economy and rising trade, supply chain and conflict risks? When markets are priced for perfection – what happens when reality intrudes. I see bad things arising.
Suddenly global markets are reeling – waking up to the reality of the unwinnable Iran War. What will a dramatic shift in sentiment mean for stocks, bonds and commodities as stagflation beckons, and Trump finds himself isolated? There is a growing risk of a liquidity shock to global markets.

The outlook for markets remains dire.. no worries! But what chance governments, central banks, the economy and growth enablers suddenly turn up the good news and put it all right again…? Are we over-estimating stagflation and recession?

The risks in Ukraine are escalating as Russia shows the nuclear card – but markets are behaving as if its Russia has been backfooted as the West finally wakes-up to the threat. Russia might have miscalculated some aspects of its strategy, but it would be wrong to think much has changed – yet!


Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel