
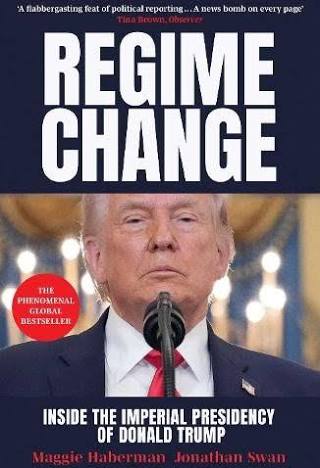
The next few months are going to get interesting as markets react to the ongoing mess that is the Gulf, rising oil prices, wobbling stocks, rising bond yields, broken supply chains, and the reassessment of the AI “revolution”. Meanwhile, the US political cycle goes into the Mid-Terms. I would suggest everyone reads Regime Change, the new book on Imperial Trump, to understand what the last 18 months has been about.

There is no stopping a market believing what it wants to believe. Tariffs, Trade Wars, Credit Cockroaches, BTC delusions, this market has it all, yet everyone is still dancing. Best thing to do might be to “Catflap” – walking away without saying anything to anyone.

Donald Trump never disappoints in terms of “interesting”. MAGA/Trump might unravel, and Trump spontaneously combust, due to Epstein – but conflict was what we knew Trump would bring to the table. The real risk to markets is probably the US Consumer. They are not as resilient as the rosy earnings season thinks.

Trump has been the dominant influence on markets thus far in 2025. That won’t last forever as inevitable Trump fatigue will set in, and the consequences of his actions become clear. That’s likely to expose a very different mood – and one that may trigger a correction to reflect the new realities.
The German elections highlight the dangers of coalition politics – swimming in a sea of treacle to agree policy choices as the likelihood of bad compromises rises. Even as Trump and Ukraine roil and destabilises the European Union, Germany is set for the distinct possibility nothing much changes. It is not strong and stable leadership at a time when it is desperately needed.

The US equity market now stands at over 70% of global market cap – is that sustainable? Many folk think not – concerned about overvaluations, speculation and geopolitics, but my great chum Julian Wheeler digs through the many reasons it became inevitable and will likely be sustained.

Market predictions are hostages to fortune. Keeping an open mind and being adaptable is an alternative – but means missing the long-term benefits of conviction trades. This morning Bill and Julian demonstrate why markets exist: perspectives differ!

Delighted to hand this morning’s Porridge to my colleague Julian Wheeler, who reminds us not to fight the Fed, making the argument against deep recession and for stock market upside. Markets are about differing views and perspectives – and despite my latent bearishness, I find myself in agreement with much of what Julian says.

Stocks tumbled 20% in H1, but Central Banks are fixated on Inflation as the No 1 priority with higher interest rates nailed on. Supply chain issues remain difficult, meaning corporate earnings will remain under pressure. The market is setting up for further weakness through H2.

Seven factors to understand the market shift that’s roiling markets; bond yields and inflation, distortion, recovery, leverage, tech vs reality, exuberance, and value.


Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel