
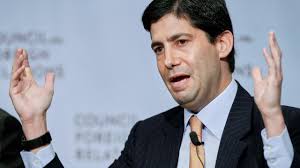
The nomination of Kevin Warsh as next Fed Chair has been rationalised as positive for stability and managing Trump. But will a new name on the desk means certainty will return? Nothing really changed within the Administration – Trump remains Trump and has a massive War Chest to fight the coming bitter Midterms.

Trump has shattered conventions on politics and diplomacy so why not financial markets as well? The Show Trial of Jerome Powell will see Trump seize the levers of monetary policy. For markets its dead simple – what will it mean for the economy and the rising prospects of a Stagflationary Bust in the US?

The end of the exceptional American Century is happening faster than we think. America is dispensing with friends and allies, and American Tech leadership is no longer unquestioned. It spells rising instability and threats. Defence has never been more critical as Europe seeks to define its future.
Gold Prices stumbled earlier this week. It is a bursting bubble? Nope. Markets will remain uncertain – while the world’s geopolitical polarity is shifting Gold remains the safe-haven play. That shift is being accelerated by events as the stability that fuelled the last 80 years of growth is undermined by bad politics and division.
The Gaza deal is an extraordinary win for President Trump. Banging heads together worked – and may have created conditions for the Middle East to move towards reconciliation. But, we had another “judder” moment as the trade conflict he triggered with China threatens to overturn the USA’s economic resilience.
Earlier this week the US Fed eased interest rates under pressure from President Trump. There are host of confusing signals around employment and price stability, but the Fed jumped anyway. The bond market sold-off – a polite growl that was just enough to warn it’s not happy about political interference and potential policy mistakes. When it barks.. it will be for good reason.

This will be the last FOMC as we knew them. From here on, a politicised Fed will be dancing to the President’s tune. That may be a good thing – but probably not. It may prove great news for markets, but a route to economic stagnation. It may also trigger a correction.

Everyone knows Europe is finished. Over-regulation, bureaucracy, a demographic bust, dusty old industries and the prospect of slow lingering decline.. Nonsense. The Sun may shortly rise on new prospects and growth as geopolitics and new trade develops. Might be time for the great rotation back across The Pond.

The Fed has fallen. What will negative real yields do the US economy? It will likely further fuel asset speculation and lead to renewed QE as global buyers exit the US bond market. Using inflation to wipe the budget deficit may even be part of the plan. The path ahead looks increasingly fraught. Been here before.

While Trump fumes at Jay Powell for not slashing rates, Scott Bessent is the adult-in-the-room minding the Fed isn’t too battered by the President’s harangues. No doubt they chat about the structure of the market and the rising risks to it – including stablecoins.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel