

Defence has become the hot new sector, but investors need to understand the geopolitical reality, military requirements, the need for adaptation, and how the battlespace is changing. Defence needs to connect capital to warfighting capabilities that can be deployed now, adapted swiftly, and manufactured in unprecedented volume. The most effective way for the West to win is to demonstrate the will and ability to do so – which is the most likely way to deter our enemies from attacking.

The current summit between Trump and Xi will likely become little more than a footnote in the history of the end of one economic empire and the emergence of the next. Xi has patience and has visited DC to let Trump do his thing, while he seeks time and stability to firmly establish China’s dominance. He is guided by the Sun Tzu dictum “Never interrupt your enemy while they are making mistakes.”
The coming year is likely to be shaped by higher inflation from energy and El Nino, rising interest rates, “policy-mistake” risks, and revaluation risks as capital markets adapt to rate normalisation. Looming over it all be political noise. Understanding where we are, how we got here and what happens next will be critical.
Celebrate Dolly. A reminder of real American exceptionalism and authenticity. What will replace her in the new America where Mega Tech and AI can settle the wrongs they do with no-liabilities settlements? Where the Vice President is a manufactured product of Billionaire’s Libertarian philosophy? Where the President runs the country as a fief to be milked dry? But can Authenticity can be bought and sold by the yard? At some point the people are going to question what’s really happening.
One rule of finance is “follow the money”. The ructions and rising doubts on the sustainability of the US Treasury Market and dollar in the evolving post-US era economy means it may be time for investment transition strategies – where will the future lie? What aspects of US and other Western Democracies will thrive, and how much more investible will China and, perhaps, India become? What are the risks?
19 months of Donald J Trump have been extraordinary – the unravelling of alliances, the forever war with Iran, and the belated discovery that financial clout doesn’t translate into geopolitical power. While the Mid-terms may make Trump a lame-duck, the consequences of Trump will hamstring the USA for decades and colour a new economic reality.
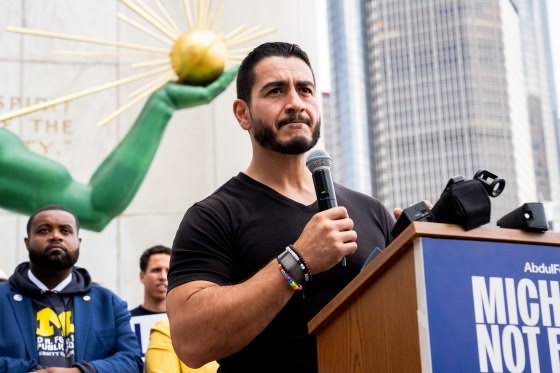
The tide of American Politics has turned dramatically extreme in recent days. The narrative is no longer about why Trump is haemorrhaging electoral support but has shifted to whether the Democrats can unite to win the Midterms in November and present a credible challenge to Trump’s MAGA successor in the 2028 presidential election. The coming gladiatorial contest between Right and Left populists will be watched closely by concerned global investors.

In the past 15 years the US economy has left Europe in the rear-view mirror. While America booms, Europe appears to be flatlining. The question is why? Americans say it’s entirely Europe’s fault: bad policies, failing politics, and lack of unity. However, the consequences of the (as yet unresolved) European Sovereign debt crisis triggered by the Global Financial Crisis of 2008 was the speedbump.

What Football fans would not want Donald Trump supporting their team? Who would say no to Trump’s superpower to reverse any referee decision? His intervention into the World Cup leaves the rest of the world shaking its collective head in disbelief. Another reason to laugh at America. These things have consequences. When is America going to wake up?
There were a number of “Moments” over the Weekend. A Peace Deal in the Gulf was inevitable – but we will see energy supply chains slowly normalise and lower inflationary expectations. Equally important is the US Government switching off Anthropic’s most powerful AI models. Collectively, these two events could have enormous consequences in terms of global power and hegemony.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel