Investing in defence was a sadly neglected skillset for many years following the end of the Cold War. Defence primes became utility like seeking to preserve margins as real budgets declined on the peace-dividend. The War in Ukraine has highlighted many things, but critically that what the Primes are selling isn’t what’s going to win the next War. To invest in defence – you need insights into the future of the battlespace.
To understand markets and the economy you need to understand how it really works; the where, what, when, why and how of the frictions that make for imperfect markets interreact. That includes politics. But trying to explain these factors is now subject to Social Media censorship – the reality is a distributed Ministry of Truth straight out of 1984. Social media now determines who can talk about markets and what they can say. Referring to incompetent politics gets you banished to the outer limits of conspiracy finance!
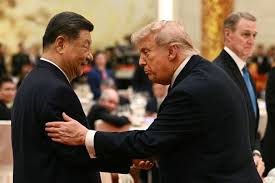
Trump has told us how fantastic the Beijing summit was – but what is the truth? China and the US agreeing on trade and growth over conflict is positive. They will remain polite to each other, but the struggle for hegemonic power will continue. Xi may be betting the state of the US economy, and the mistakes in Iran, means Trump will become less relevant from November.

The imminent departure of Sir Keir Starmer (it is a matter of when, not if) is bread and circuses. His defenestration will distract and amuse the chattering political classes and infuriate voters as yet more evidence of Broken Britain. But we need to be honest – it's not any single “leader’s” fault. 60 years of bad decisions piled on poor policies have landed the UK in the mire of the present. It can be fixed – but it will need a reset.
Today is the 81st anniversary of VE Day – the end of the Second World War in Europe. Markets are fixated on rising stock prices and probably won’t notice. Complacency is the danger. The Wars in Ukraine and Iran highlight success and failure and point towards a very different future world than the expected one. There are massive implications for markets – but that’s a tomorrow problem for markets focused on “now”.

When staring down the abyss of looming stagflation, a bond market rout, and a reset on the global economy… let’s try to pretend it’s all something else. Christine Legarde would have made a great French President. Of course it’s not Stagflation... it’s just... Well? What is it?
Defence is among the most difficult areas to invest. Who would become an analyst after 30-years as a Cinderella sector in the wake of ESG and peace dividends? Now, the imperative for new defence investment is crying out for private capital. That puts a clear premium on knowledge, contacts and skill to invest. Here is a solution.

Viktor Orban was a curious beast. A pragmatist and a populist who tried to play off Moscow, Washington and Brussels. Hungary is not yet solved, but it could be a transformational moment for Europe in terms of Populism and Unity.
Pretty much as was expected Donald Trump has declared his war almost over. Its not. It has destabilised the global economy. What might be roiled in its wake? One area to watch is how a liquidity default-storm in Private Credit could infect global bond and equity markets, causing a global market crisis.
As the US and Israel attack Iran, confirming the Fire Horse threat of escalating conflict risks, do we also face a second social threat from AI triggering widespread social and wealth-inequality protests? Does 2026 risk becoming a double whammy hit on market sentiment and confidence?

Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.
If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel