

What should markets be thinking about Andy Burnham’s conference speech yesterday? Gilts look to be giving him the benefit of doubt. Good in parts? He spoke well, proposed some positive policies and ideas, and gave an impression of a confident, positive politician set to deliver. The real issue isn’t just can Labour hold the nation steady and reverse years of negativity and low growth, but can any of the other parties do any better given the constrained state of the national finances?

Global Bond yields remain… fragile. As the US breaches 5% 10-year yields, the UK is now slowing QT which should be market positive. It’s high time the Bank of England and the UK Treasury (which famously pretend the other doesn’t exist) cooperate on liability management to address the UK’s debt pile – which is actually in much better shape than the right-wing press would have you believe.
Fifty years of political dither leaves the UK looking broken. Faced with massive constrains from taxation and bond markets, there are limited choices from tinkering with spending while trying to look good enough ahead of the next election. Britain needs something more radical – and a complete reform of the system and process.
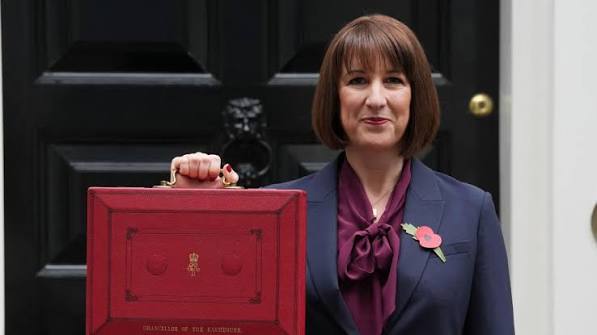
Andy Burnham promises the UK a national reboot. Critical to his success will be his choice of chancellor, and the relationship with the financial markets. Rachel Reeves is closely associated with the failed Starmer premiership – but she knows how to do the job and has credibility with the markets. With new leadership she could prove a much better choice than other contenders.

Western economies succeed because bond and stock markets work together. Bond markets enable governments to finance the optimal conditions for invention and innovation, enabling growth and prosperity. Sometimes Markets fall out of line, while Politics are ruled by votes rather than experience – and that’s where the wobbles start to multiply.
In Bonds there is truth. While government bond yields have risen some 40-50 basis points since the Iran War, and yield curves have steepened, we are not in crisis territory yet. However, the risks of “higher for longer” rates, and sustained inflation have risen. These will impact credit markets and potentially trigger a cascading corporate crisis – leading to all kinds of hell that governments and central banks are now ill-equipped to deal with.
The UK is not about to disappear in a puff of smoke because the Gilts Market is having a minor tantrum. But there is a serious Political Competency premium on Gilts, which will rise when the scale of Labour’s defeat becomes apparent, and the Starmer premiership is up against the wall. Trouble ahead.

The spike in Gilt Yields says it all. Its crisis – again – in Westminster as Starmer is mired in crisis with no obvious way out. Yet again we learn a political lesson – good political leaders are a scarce commodity. The British electorate is losing faith in politics. What will global investors think?

The Russians have captured the FT, apparently! The headline that Gilts are about to crash because the Government will borrow more to increase defence spending is Pravda 101. The reality is Gilts should rally on increasing the strategic deterrence that defence spending will create.

The threat board is looking crowded this morning. From UK political risk, escalating conflict risks, a possible credit burp and what happens next in unsustainable narratives – who knows what further No-See-Ums lurk in the background. Yet markets party on. What can possibly go wrong…..?
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel