
It really does feel the Atlantic Ocean got much, much wider. As Europe struggles with riots and populism, financiers in the USA dismiss Yoorp as irrelevant, and think their economy is doing just great, fuelled by the AI boom and rising earnings. What they miss is the vulnerability of the economy to a debt shock and rising Treasury refinancing risk.

In Bond Markets there is truth – and they are flashing warning signals a systemic market reset is on the cards. As rates rise, the relative prices of all financial assets will be impacted as the price of money normalises. It’s a period of transition with a high chance of an unstable reset, which is magnified by QE setting a false expectation of long-term low rates, and the growing realisation financial systems will suffer from political incompetence.
The media has us all convinced Western Economies are on the verge of a bond meltdown. However, what is really happening is The Great Bond Market Normalisation – a return to real interest rates that reflect the global economy and where nations are. The big risk is that repricing government bonds will crash currently absurd valuations across other financial assets – precipitating a wider market crisis.
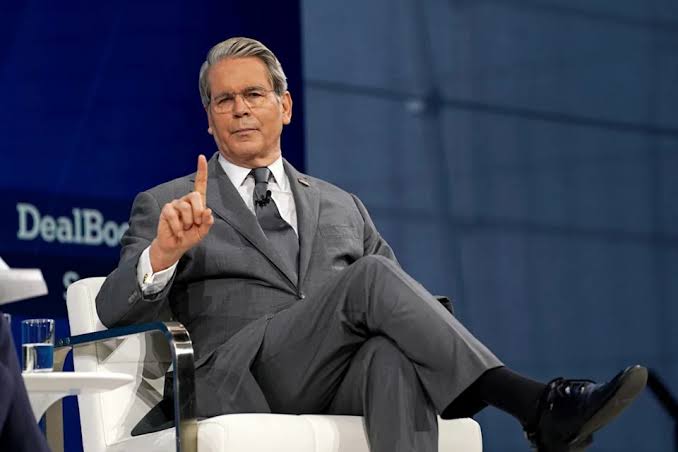
With US debt about the breach $40 trillion, Scotty Bessent intervened to stem rising long-end yields. The market loved it, but the reality is that distorting interest rates has all kinds of consequences. That includes the risk an economy focused entirely on financial returns isn’t spotting or addressing real world threats to jobs, growth, conflict, the environment and climate. Maybe it’s time to let rates normalise?
In Bonds there is truth. While government bond yields have risen some 40-50 basis points since the Iran War, and yield curves have steepened, we are not in crisis territory yet. However, the risks of “higher for longer” rates, and sustained inflation have risen. These will impact credit markets and potentially trigger a cascading corporate crisis – leading to all kinds of hell that governments and central banks are now ill-equipped to deal with.

UK Chancellor Rachel Reeves is being blamed for the Gilt Bear market. Harsh and unfair – it’s a global thing. Investors fear sticky inflation as much as rising debt quantums, tax cuts and spending plans. A global bond bear market brings consequences – be aware of them.

A big question for 2025 is how resilient the US Treasury market will be to tax cuts, spending hikes and the deficit surpassing $40 bln in 2026! Trump is going to slash spending – taking tips from Argentina’s Javier Milei. Will it work – and is it suitable policy? Here in the UK, govt is taking tough decisions, but we are poised at the edge of the rabbit hole as polarisation looks set to dominate!

This is shaping up as another tense week on the ongoing uncertainty of the US Election. Harris or Trump? Equally important - will either win the whole suite of White House, Senate and Congress, avoiding political gridlock, but potentially unleashing a deluge of uncertainty on the US Bond market?

Make the world a better place by enabling women on International Women’s Day! And, Bond Markets need to a rethink.

Markets look distinctly soft, and vulnerable to further downside pressure. The gaps between value, hype and narrative are becoming clearer – spelling opportunity, but also raising the risk of a crash.


Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.
If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel