
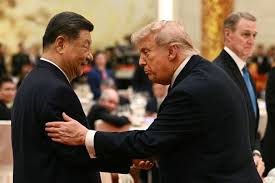
Trump has told us how fantastic the Beijing summit was – but what is the truth? China and the US agreeing on trade and growth over conflict is positive. They will remain polite to each other, but the struggle for hegemonic power will continue. Xi may be betting the state of the US economy, and the mistakes in Iran, means Trump will become less relevant from November.

Trump is running out of options over Iran. Bluff and Bluster won’t fix it. When he visits Beijing this week, he will be up against Emperor Xi – who holds all the cards; sufficient oil reserves, dominance over global supply chains, and critically the ability to shut off the single most important commodity in the world today – Chips.

That was an interesting weekend. Trump announces a blockade that will impact the whole Global Economy – and South East Asia and China in particular. At least Europe got some good news from Hungary. More instability forecast before Trump inevitably TACO’s again. Markets are getting bored of it – which means the consequences could be even more volatile! That could double up No-See-Um Risks.
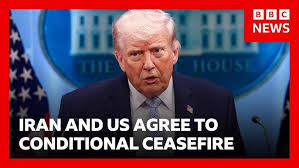
Trump took the Off-Ramp. Markets are soaring, off to the races as the threats of global slowdown, recession and stagflation recede. But, for all the military power and competency on display – it’s a strategic defeat for the USA. That has massive implications for US Assets – Treasuries, Stocks, Investment, Market Confidence and Politics.
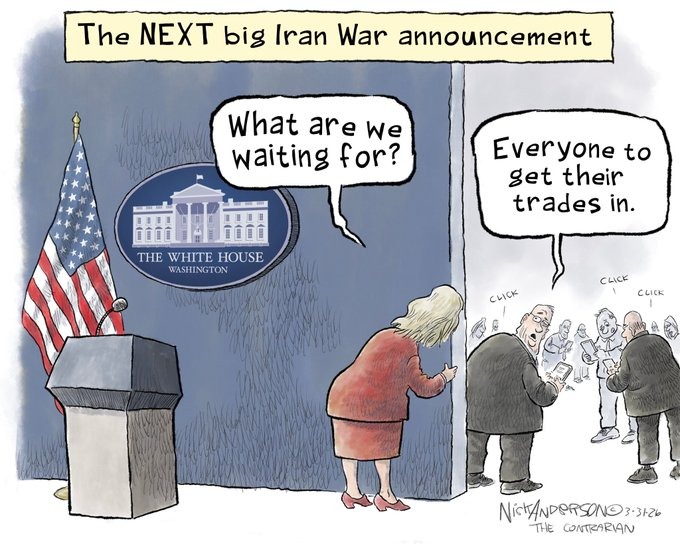
Oh dear. Last night’s explanation of the War did not go well. What changed except a more unstable and fractured global economy and rising trade, supply chain and conflict risks? When markets are priced for perfection – what happens when reality intrudes. I see bad things arising.

Who needs nukes to win an Oil War when Water is the key? The Front-Line Gulf States are highly vulnerable to a Water War on their desalination plants. Yesterday Trump threatened to strike Iran’s water infrastructure – practically inviting Tehran to strike back! But the Strait of Hormuz is not Iran’s only Ace in the current war.
The future will be set not just by the defence and deterrence discussions last weekend in Munich, but by how global markets react to competition. New Chinese AI drops from DeepSeek and Qwen may challenge US hyperscalers and challenge expectations of global demand and markets.
Gold surges through $5000 and markets remain distracted by the sturm et drang of words and events. The world is changing – but are we thinking about all the wrong things? The real issue for the future may be investment choices between authoritarian states vs nimble democratic nations.
Yesterday was a strategic disaster for America. Trump and his minions have destroyed the alliances that underpinned American exceptionalism. He revealed himself as weak and venal; an old man lost in rambling hatreds. America now faces a scrabble to save face and recover a modicum of respect. The medium-to-long term market implications are huge.
It’s one year since Trump took office for a second time. It’s been dramatic. It’s been eventful – and it’s been destructive and destabilising. The winners are Putin and Xi. The losers are the West. But have we now reached peak-Trump? Europe is the key – the continent has to wake up to the coming opportunities.
Disclaimer
This publication is protected by US, UK and International Copyright laws. All rights reserved. No License is granted except for the subscriber’s personal use. Rights will be pursued.
The Morning Porridge is not investment advice. It is market commentary based on discussions and information gathered from multiple sources believed to be reliable. No guarantee is given for its accuracy or completeness. It is not an offer to buy, sell or solicit investments or securities. The author may have a position in companies or institutions discussed in this commentary.

If you want to know what’s really happening and why.. welcome to the Porridge.
Financial Market Insights for Thinkers!
© Morning Porridge | All Rights Reserved | Website Design & Support by Orange Pixel